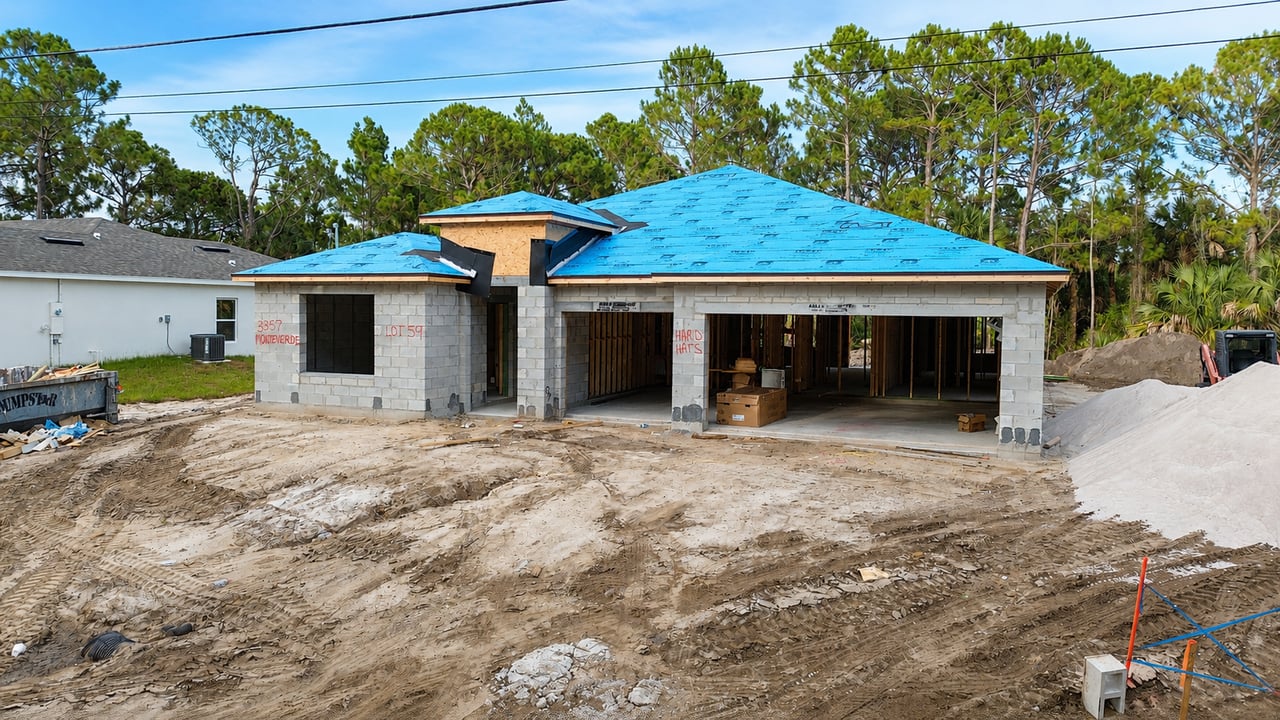
The Complete New Construction Home-Buying Playbook for FHA and VA Buyers in Palm Bay and Brevard County
This guide is for educational purposes. Builder incentives, interest rates, mortgage guidelines, construction timelines, warranties, inventory, and contract terms can change. Your specific purchase agreement, loan documents, and warranty documents will control your transaction.
My name is Donell Knight II, and I am a local Realtor with Blue Marlin Real Estate here in Brevard County.
I was born and raised on the Space Coast, and I have lived in Southeast Palm Bay since 2008. Over the years, I have helped buyers purchase everything from older resale homes to completed new construction, inventory homes already being built, and homes that were still months away from being finished when we signed the contract.
And I can tell you this honestly:
Buying new construction is not as simple as walking into a model home, choosing a floor plan, and signing whatever the builder puts in front of you.
The home may be brand new.
The process is not always simple.
A new construction buyer may need to understand a builder-written purchase agreement, preferred-lender incentives, FHA or VA financing requirements, construction timelines, deposit rules, lot placement, well and septic systems, independent inspections, blue-tape walkthroughs, punch-list repairs, appraisal risk, builder warranties, property taxes, insurance, closing deadlines, and what happens when work is still unfinished on closing day.
That is a lot to think about while you are also trying to decide whether you like the kitchen cabinets.
My job is not just to help you find a new home.
It is to help you understand the complete transaction.
I help buyers compare builders, evaluate incentives, review the important business terms of builder contracts, coordinate with FHA and VA lenders, investigate the home and lot, negotiate better terms, schedule inspections, attend walkthroughs, document construction issues, monitor deadlines, and make sure the house, financing, payment, warranty, and contract all work together.
Because a builder may advertise $20,000 toward closing costs and a reduced interest rate.
That sounds great.
But I still want to know:
Is the advertised rate permanent or temporary?
How many discount points are being charged?
Does the buyer have to use the builder’s preferred lender?
Are property taxes, homeowners insurance, prepaid interest, and escrow reserves included?
What happens to any incentive money the buyer cannot use?
Does the price still make sense when we review comparable sales?
Is the home on city water, private well, sewer, or septic?
Are the refrigerator, washer, dryer, blinds, gutters, irrigation, fence, and water-treatment equipment included?
Can the buyer hire an independent inspector?
Can unfinished punch-list work delay closing?
What does the builder warranty actually cover?
What happens if the buyer’s lender is not ready on the builder’s required closing date?
The advertisement gets your attention.
The contract tells you what you are actually agreeing to.
This guide is designed to walk you through all of it.
Not just how to qualify for an FHA or VA mortgage.
Not just how to choose a floor plan.
The complete new construction process here in Palm Bay and throughout Brevard County, from the first builder visit through financing, negotiations, inspections, blue tape, appraisal, closing, warranties, and eventually receiving the keys.
So grab a coffee.
This one is going to be thorough.
Who this guide is for
This guide is for you if you are considering a new construction home in Palm Bay or anywhere in Brevard County and plan to use FHA or VA financing.
You may be looking at a completed inventory home that has never been occupied. You may be considering a house that is already under construction. You may be selecting a lot and waiting for the builder to begin. You may also be comparing a smaller independent builder against one of the larger production builders operating throughout Palm Bay.
Maybe the builder is offering to pay your closing costs.
Maybe you saw a lower interest rate advertised online.
Maybe you want a new home because Florida homeowners insurance has made some older properties difficult or expensive to insure.
Maybe you simply do not want to move into a home and immediately replace the roof, air conditioner, water heater, electrical panel, and plumbing.
All of those are legitimate reasons to consider new construction.
You do not need to become a builder, mortgage underwriter, home inspector, warranty specialist, insurance broker, and contract expert before buying.
But you should have somebody on your side who understands how all of those pieces connect.
First, what kind of new construction are we talking about?
People use the phrase “new construction” to describe several completely different purchases.
You might be buying:
- A completed home that has never been occupied
- An inventory home currently under construction
- A to-be-built home on a lot controlled by the builder
- A custom home being built on land you already own
- A home using construction-to-permanent financing
This guide primarily focuses on the first three.
That is the typical Palm Bay builder transaction.
The builder owns or controls the lot, constructs the home, and sells the completed property to you at closing. Your FHA or VA mortgage is normally used to purchase the finished property rather than fund individual construction draws.
That is very different from buying land, hiring your own contractor, and using a construction loan to finance the project from the ground up.
Same general words.
Very different transaction.
Why new construction can work so well for FHA and VA buyers
The obvious benefit is that you are purchasing a brand-new home.
The roof is new.
The electrical system is new.
The plumbing is new.
The HVAC system is new.
The appliances may be new.
The home may also have modern wind-mitigation features that help it qualify for a more favorable insurance quote than an older property.
But financially, the biggest opportunity may be the builder’s incentive.
A normal resale seller may agree to pay some of your closing costs, but that seller is usually an individual homeowner. They may have limited equity. They may need a specific amount from the sale to purchase their next home. They may also take a request for $15,000 or $20,000 personally because every dollar comes directly from their proceeds.
Builders often look at the transaction differently.
A builder may be trying to close a home before the end of the month or quarter. The home may already be completed and costing the builder money every day it remains unsold. The builder may have multiple homes with the same floor plan. The company may want to preserve the recorded sales price instead of advertising a visible price reduction.
That can create room for the builder to contribute toward:
- Closing costs
- Prepaid expenses
- Tax and insurance escrows
- Discount points
- A permanent interest-rate buydown
- A temporary rate buydown
- Appliances
- Blinds
- A privacy fence
- Additional cabinetry
- A refrigerator
- A washer and dryer
- Selected upgrades
- Other negotiated items
The opportunity can be significant.
But the incentive still has to be structured correctly.
Builder incentives are not free money
Let me clear something up.
When a builder advertises $20,000 or $30,000 in incentives, the builder is not normally handing you a check at closing.
The money must usually be applied toward eligible expenses. The exact use depends on the builder’s addendum, your lender, your loan program, your actual closing costs, the contract price, and whether you are required to use the builder’s preferred lender or title company.
Unused money is commonly forfeited.
It generally cannot be handed back to you as cash.
It normally cannot simply replace your required FHA down payment.
And it does not necessarily reduce the purchase price unless the builder agrees to restructure the deal.
In one Palm Bay production-builder contract I reviewed, the buyer’s package included $24,000 in stated incentives that could be applied toward closing costs, prepaids, and an interest-rate buydown. The package was designed around a preferred financing arrangement.
That sounds impressive.
And it can be.
But I still want to break down exactly where every dollar is going.
Let’s say the buyer receives $20,000.
The normal closing costs and prepaids total $13,000.
That leaves $7,000 potentially available for a rate buydown, depending on lender and program rules.
Now imagine the buyer’s normal costs are only $9,000 and the lender cannot use the remaining $11,000 effectively.
That headline incentive may be larger than the actual benefit.
Every available dollar should have a job.
FHA and VA contributions do not work exactly the same way
FHA and VA both permit sellers or builders to pay eligible buyer expenses, but the programs use different rules.
FHA generally allows an interested party, including a builder, to contribute up to 6% of the sales price toward eligible closing costs, prepaid expenses, discount points, and other permitted items. The contribution still cannot exceed the buyer’s actual eligible costs, and excessive inducements can affect the transaction. FHA’s minimum down payment generally cannot simply be replaced by the builder’s contribution.
VA uses a different framework.
The often-repeated “4% VA concession limit” does not necessarily mean the seller can pay only 4% of all buyer closing expenses. VA separates ordinary allowable closing costs from certain items classified as seller concessions. The lender must structure the total package correctly.
That distinction is important because a builder may be able to pay ordinary allowable expenses in addition to concessions that fall under the separate percentage limitation.
The lender should calculate the structure.
I help make sure the builder, lender, and contract are all talking about the same numbers.
The advertised interest rate may not tell the full story
A builder may advertise a rate that appears dramatically lower than the rest of the market.
Before I get excited about it, I want answers.
Is it a permanent rate for the full loan term?
Is it a temporary 2-1 or 3-2-1 buydown?
Does the buyer have to use a specific lender?
Is the rate available to FHA, VA, or only conventional borrowers?
What credit score is required?
How large is the loan?
How many discount points are being paid?
Is the builder using part of the advertised closing-cost incentive to buy the rate down?
How long is the rate locked?
Who pays if construction is delayed and the rate lock expires?
A temporary buydown lowers the buyer’s effective payment during the first few years, but the underlying note rate does not change.
A permanent buydown reduces the note rate for the life of the loan.
Those are not the same benefit.
A lower rate can be extremely valuable.
But I do not compare rates in isolation.
I compare:
- Interest rate
- APR
- Discount points
- Origination charges
- Mortgage insurance
- Funding fee
- Monthly payment
- Cash to close
- Builder incentive
- Rate-lock period
- Extension risk
- Loan-program requirements
The lowest advertised rate is not automatically the least expensive loan.
Should you use the builder’s preferred lender?
Sometimes the answer is yes.
The builder’s lender may have access to a forward commitment or special pricing that an outside lender cannot reproduce. The builder may also contribute significantly more when the buyer uses the preferred lender and title company.
That combination can create an excellent deal.
But I do not automatically assume the preferred lender is the best choice just because the incentive is larger.
An outside lender may have:
- A lower base rate
- Lower origination charges
- Better mortgage-insurance pricing
- More flexible underwriting
- Better communication
- More experience with the buyer’s income
- A stronger understanding of VA entitlement
- A better plan for a credit-challenged FHA buyer
- Less risk of a last-minute denial
One smaller-builder contract I reviewed stated that the builder would pay the buyer’s allowable closing costs when the buyer used the builder’s preferred lender. However, the negotiated language excluded prepaid taxes, homeowners insurance, prepaid interest, and initial escrow funding.
To a buyer, “closing costs paid” may sound like “I need almost nothing besides my down payment.”
Then the buyer receives the final numbers and discovers that several thousand dollars of prepaids and escrows were never included.
Words matter.
We compare the complete Loan Estimates, not just the promotional flyer.
Why I want financing reviewed before we negotiate
I do not want the first serious review of your finances to happen after you have signed a builder contract and delivered a deposit.
For an FHA buyer, we need to understand:
- Credit score
- Debt-to-income ratio
- Income documentation
- Employment history
- Available funds
- Down payment
- FHA mortgage insurance
- Comfortable monthly payment
- Potential interest-rate options
- Whether credit improvement would materially help
For a VA buyer, we may also need to review:
- Certificate of Eligibility
- Full or remaining entitlement
- Current VA-financed properties
- VA funding-fee status
- Residual income
- Disability income
- Military allowances
- Occupancy plans
- Lender overlays
- Whether a down payment may be required because of partial entitlement
A buyer can be technically preapproved and still be in a weak position.
Maybe the approval leaves the buyer with no savings.
Maybe one credit-card payoff would materially lower the monthly debt.
Maybe a 20-point credit-score improvement would produce better pricing.
Maybe the buyer can afford the purchase price but not the payment after property taxes, insurance, HOA dues, and mortgage insurance are included.
Approval is not the same as readiness.
Preapproval first.
Always.
The builder’s sales representative does not represent you
This is one of the biggest misunderstandings in new construction.
The person in the model home may be extremely knowledgeable.
They may know every floor plan, elevation, cabinet selection, construction stage, and available lot.
They may be responsive, friendly, and genuinely want you to have a good experience.
But they represent the builder.
Their responsibility is to sell the builder’s home under the builder’s terms.
They are not responsible for advising you that:
- Another builder may have a stronger incentive
- The contract gives the builder broad termination rights
- The deposit may be difficult to recover
- The preferred lender’s rate may not be competitive
- The inspection rules are unusually restrictive
- The advertised incentive excludes prepaids
- The warranty may be weaker than another builder’s
- The lot may limit a future pool or fence
- The tax estimate may be too low
- The property could be on well and septic
- Unfinished punch-list items may not delay closing
- A buyer-caused closing delay may trigger a daily charge
That is not an attack on the sales representative.
It is simply not their job.
My job is to look at the transaction from your side of the table.
Bring your Realtor on the first visit
Many builders require the buyer’s agent to register the buyer during the first visit, online inquiry, appointment, or meaningful contact.
Do not assume we can tour with you after you have already visited several times, negotiated directly, and signed paperwork.
By then, the builder may refuse to recognize your representation.
The easiest solution is simple.
Tell me before you visit.
I can register you, attend the appointment, help compare the available homes, ask questions, and make sure we understand the full incentive before the conversation moves too far.
You still get to enjoy the model home.
You just do not have to decode the transaction alone.
The website price may be only the beginning
A builder may advertise a base price.
That number may not include:
- Lot premium
- Elevation premium
- Structural options
- Design-center selections
- Additional clearing
- Longer driveway
- Utility connection expenses
- Water-treatment equipment
- Irrigation
- Gutters
- Refrigerator
- Washer and dryer
- Blinds
- Fence
- Screened lanai
- Closing costs
- Prepaid expenses
- HOA contributions
- Rate-lock extensions
A completed inventory home may already include several upgrades in the final price.
A to-be-built home may begin with the base plan and increase as the buyer adds options.
This is why I want the actual selection sheet and included-features list.
The model home is designed to show the builder’s possibilities.
It may contain tens of thousands of dollars in upgrades.
The model gets you excited.
The features sheet tells you what is included.
Palm Bay is not one uniform new-construction market
Palm Bay is geographically large, and utility availability can vary significantly from one area to another.
One home may have city water and city sewer.
Another may have city water and septic.
Another may have private well and septic.
The City of Palm Bay recommends verifying utility availability for the specific property. When centralized service is unavailable, well and septic feasibility may require review through the applicable environmental-health authority.
This affects much more than where the water comes from.
It can affect:
- Monthly utility expenses
- Water quality
- Water softening or treatment
- Septic maintenance
- Drain-field placement
- Fence placement
- Pool placement
- Home placement
- Driveway location
- Landscaping
- Future additions
A home being on a well is not automatically a problem.
But you should know it is on a well before closing.
You should know whether a water softener or treatment system is included.
You should know where the septic tank and drain field are located.
You should also know whether the backyard you are picturing can accommodate the pool, fence, shed, or outdoor living space you want later.
Ask what “city water” actually means
A home being advertised as “city water” does not automatically mean it also has city sewer.
Some Palm Bay properties may have city water with a private septic system.
Those are two separate questions.
I want to confirm:
- Water source
- Wastewater system
- Connection status
- Meter or utility fees
- Septic location
- Drain-field location
- Water-treatment equipment
- Any special assessments or connection obligations
Small question.
Potentially large difference.
Lot placement is usually controlled by the builder
Buyers are often surprised by how much control the builder keeps over the lot.
A builder contract may reserve the right to determine:
- Where the home sits
- Whether the garage faces left or right
- Whether the floor plan is mirrored
- Where the driveway is located
- How the lot is graded
- Which trees are removed
- Drainage patterns
- Utility-box locations
- Mailbox locations
- Drainage-inlet locations
- Septic and drain-field placement
The local production-builder contracts reviewed for this guide gave the builders broad discretion over home placement, orientation, material substitutions, and reasonable differences from models or promotional materials.
Here is the plain-English translation:
Do not rely only on the model.
Review the site plan.
Confirm the garage orientation.
Confirm whether the floor plan is mirrored.
Confirm the water and septic arrangement.
Confirm what is included in writing.
The home you toured may not sit on its lot exactly like the home you are purchasing.
“Substantially similar” does not mean identical
Builder contracts commonly promise to construct a home that is “substantially similar” to the selected model, plan, specifications, or features sheet.
They also commonly allow substitutions of materials or products that the builder considers equal or comparable.
There are legitimate reasons for this.
Products become unavailable.
Manufacturers discontinue finishes.
Building codes change.
Supply chains move.
A particular appliance, floor color, cabinet pull, light fixture, or plumbing fixture may no longer be available by the time it is needed.
But “comparable” can still become a disagreement.
The buyer may believe the replacement looks less expensive.
The builder may believe it provides equal quality or value.
That is why every important negotiated item belongs in writing.
Not in an advertisement.
Not in a text message.
Not in a verbal conversation inside the model home.
In the contract, selection sheet, or a signed addendum.
There are really three deals inside one new-construction purchase
Not literally.
But this is how I explain it.
The financial deal
This includes:
- Purchase price
- Deposit
- Financing
- Closing costs
- Builder incentive
- Rate buydown
- Upgrades
- Cash needed
- Appraisal terms
The construction deal
This includes:
- Floor plan
- Elevation
- Lot
- Included features
- Materials
- Substitutions
- Completion
- Inspections
- Orientation
- Punch list
The risk deal
This includes:
- Buyer default
- Builder default
- Deposit forfeiture
- Warranty
- Closing delays
- Dispute procedures
- Attorney fees
- Damage limitations
- Builder termination rights
- What survives closing
Most buyers study the first deal.
The last two are where the surprises live.
Smaller builders and larger builders may use completely different contracts
A smaller independent builder may agree to use the standard Florida Realtors/Florida Bar contract.
That can provide the buyer with familiar sections addressing financing, inspections, title, closing, default, and final walk-through.
Specific new-construction promises may then be added in writing.
In one Palm Bay transaction reviewed for this guide, the smaller builder agreed to terms covering a one-year workmanship or labor warranty, a ten-year structural warranty through 2-10 Home Buyers Warranty, a blue-tape walkthrough, a home orientation, included appliances, and a preferred-lender closing-cost contribution.
A larger production builder will usually use its own proprietary agreement.
That contract may be 20, 30, 50, or more pages once the addenda, disclosures, selection sheets, lender incentives, warranty documents, and affiliated-business disclosures are included.
Larger-builder contracts commonly give the builder more control over:
- Construction
- Materials
- Lot placement
- Inspections
- Closing date
- Punch-list work
- Financing deadlines
- Buyer default
- Warranty remedies
- Dispute resolution
That does not automatically make the builder or contract bad.
It means we need to understand what the buyer is agreeing to.
The deposit may be more exposed than it is in a normal resale contract
Buyers familiar with resale transactions often expect a defined inspection period and financing period during which the deposit can be recovered.
Builder contracts may operate differently.
In one local production-builder agreement, the buyer had to apply for financing within three days and provide a loan commitment within 30 days. The agreement stated that the buyer’s clearest path to a refund was obtaining a written loan denial and delivering it before the contingency deadline. Failure to close later because financing was unavailable could result in the deposit being retained by the builder.
That is very different from assuming:
“My loan is not approved, so I automatically get my money back.”
Maybe.
Maybe not.
It depends on the contract and whether the buyer satisfied every deadline and cooperation requirement.
Another large-builder contract allowed the seller to request proof that the buyer had enough available money to complete the purchase. Failure to provide acceptable proof within the stated period could be treated as a default.
A builder deposit is not necessarily a refundable reservation fee.
Before the buyer sends it, I want to understand:
- How much is due?
- When is it due?
- Where is it held?
- Is additional money required later?
- Can any portion be used during construction?
- Which cancellation rights exist?
- Which deadlines protect the buyer?
- What happens if financing is denied?
- What happens if the appraisal is low?
- What happens if the builder cannot obtain a permit?
- What happens if site conditions prevent construction?
- What happens if the buyer simply changes their mind?
Some builders have permit and site-condition contingencies
A to-be-built home may depend on more than the buyer’s financing.
The builder may reserve the right to terminate if:
- A building permit cannot be obtained
- The home does not fit the lot
- Setback requirements cannot be satisfied
- Unusual foundation or structural costs are discovered
- Wetlands are present
- Protected species are found
- Adverse subsurface conditions exist
- Septic approval cannot be obtained
- The builder determines construction is not practical
In the Christopher Alan Homes agreement reviewed for this guide, the seller had a permit contingency and retained termination rights if certain environmental or subsurface conditions were discovered. If the builder terminated under those provisions, the agreement called for the buyer’s deposit to be returned.
This is why the lot is not just empty dirt.
The dirt is part of the deal.
Construction dates are estimates, not promises
The sales representative may tell you that the home should be ready in five or six months.
The contract may say something very different.
One Palm Bay builder agreement estimated completion at approximately 180 days after construction began but allowed up to two years after the buyer signed, subject to extensions for certain circumstances beyond the builder’s control. The contract also stated that the builder was not responsible for certain buyer expenses caused by delays, including rent, moving expenses, storage costs, interest-rate changes, or rate-lock extensions.
Another major builder contract also provided an outside construction period of approximately two years, subject to qualifying delays.
That does not mean the home will take two years.
It means the sales estimate and contractual deadline are not the same thing.
Do not terminate your lease, schedule movers, arrange a closing-day delivery, or lock a mortgage rate based only on a verbal construction estimate.
The dirt does not care about your moving schedule.
Neither does the weather.
What can delay a new construction home?
Possible delays include:
- Permit review
- Engineering
- Material shortages
- Product substitutions
- Labor shortages
- Weather
- Hurricanes
- Utility connections
- Well installation
- Septic approval
- Site clearing
- Drainage work
- Government inspections
- Reinspection
- Certificate of Occupancy requirements
- Buyer-requested changes
- Appraisal conditions
- Lender conditions
The City of Palm Bay states that residential construction permits average approximately 14 working days for approval or an initial response, but other departmental approvals may also be required before a permit can be issued.
A permit estimate is not a home-completion estimate.
Small thing.
Big difference.
The builder may control your closing date
In a normal resale transaction, the parties usually negotiate a specific closing date.
A proprietary builder agreement may give the builder significantly more control.
In the contracts reviewed for this guide:
- One builder could schedule closing with as little as three days’ notice.
- Another set closing approximately 15 days after notifying the buyer that the home was substantially complete and available for orientation.
- The builder could advance or postpone the closing date.
- Buyer-caused delays could result in financial penalties.
The Christopher Alan Homes contract provided for a possible charge of $250 per day when the buyer failed to close on the builder’s required date and the builder elected to extend the closing.
The Maronda agreement allowed an increase calculated at 18% annually against the unpaid purchase-price balance when closing was delayed by the buyer or the buyer’s lender after the builder’s scheduled closing date.
That is not language you skim.
It affects how we manage:
- Loan approval
- Rate locks
- Insurance
- Final employment verification
- Closing Disclosure
- Cash to close
- Buyer travel
- Lease termination
- Moving arrangements
When the builder says the home is nearing completion, that is our signal to tighten every loose end in the loan.
A Certificate of Occupancy does not mean the home is perfect
A Certificate of Occupancy generally means the appropriate local authority has approved the home for occupancy.
It does not mean:
- Every paint blemish is gone
- Every cabinet is aligned
- Every door closes correctly
- Every tile is perfect
- Every appliance has been tested by the buyer
- Every drainage concern has appeared
- Every warranty issue has been resolved
- A private inspector found nothing
Builder agreements commonly define completion around the issuance of a temporary or final Certificate of Occupancy.
That means the builder may consider the home complete even if punch-list work remains.
Habitable.
Closeable.
Not necessarily flawless.
Yes, you should inspect a brand-new home
I hear this all the time:
“It passed city inspections. Why would I pay for another inspection?”
Because the municipal inspector and your private home inspector are doing different jobs.
The building department evaluates applicable code and permitting requirements.
Your private inspector evaluates the accessible home for you.
A private inspection may identify concerns involving:
- Roof installation
- Flashing
- Siding
- Stucco
- Windows
- Doors
- Plumbing leaks
- Drainage
- Electrical components
- HVAC performance
- Insulation
- Appliances
- Attic conditions
- Safety items
- Incomplete work
- Cosmetic defects
New does not mean nobody made a mistake.
It means nobody has lived there long enough to discover it yet.
The builder may control the inspection process
The local contracts reviewed for this guide handled inspections very differently.
The smaller builder used a standard FAR/BAR agreement with a negotiated inspection period.
One production builder required independent inspections to be:
- Scheduled through the builder
- Requested at least seven days in advance
- Conducted during limited weekday hours
- Completed by a properly licensed and insured inspector
- Attended by the builder or its representative
- Performed without delaying construction or closing
That agreement also restricted who could attend and treated unauthorized entry as a potential material breach.
The practical lesson is simple.
We do not wait until the last minute.
We select the inspector early.
We obtain any required license and insurance documents.
We schedule according to the builder’s procedure.
We understand which inspections are allowed.
We submit significant findings in writing.
And we understand what the builder has actually agreed to do with those findings.
Which new-construction inspections should you consider?
The appropriate inspection plan depends on when you enter the transaction and what access the builder permits.
Pre-drywall inspection
A pre-drywall inspection occurs after much of the framing and rough mechanical work is visible but before the walls are closed.
The inspector may be able to review accessible components involving:
- Framing
- Roof structure
- Plumbing lines and penetrations
- Electrical routing
- Mechanical installation
- Window installation
- Flashing
- Fire blocking
- Structural connectors
Once the drywall is installed, much of this work disappears from view.
Final home inspection
The final inspection takes place near completion and evaluates the accessible systems, components, finishes, and visible construction.
Wind-mitigation inspection
A wind-mitigation inspection documents qualifying hurricane-resistance features that may help determine the homeowners insurance premium.
Four-point inspection
Four-point inspections are more commonly requested on older homes. A brand-new home will not always need one, but the insurance company ultimately decides which documentation it requires.
Termite or wood-destroying-organism documentation
FHA and VA transactions may require particular new-construction or termite-treatment documentation depending on the home, construction stage, lender, and loan program.
HUD maintains a Builder’s Certification, a Warranty of Completion of Construction, and a Subterranean Termite Protection Builder’s Guarantee used in applicable FHA transactions.
Eleven-month warranty inspection
Some buyers order another professional inspection around the tenth or eleventh month after closing.
That gives the homeowner time to identify concerns and submit qualifying warranty requests before the one-year workmanship period expires.
I like this strategy.
The pre-closing inspection finds what is visible before occupancy.
Living in the home reveals what may not become obvious until later.
What is a blue-tape walk-through?
The blue-tape walk-through is a detailed visual review of the completed home.
The buyer and builder representative walk through the property and identify visible items that may need correction, completion, cleaning, or adjustment. Removable painter’s tape is often used to mark the locations.
Common blue-tape items may include:
- Paint blemishes
- Drywall imperfections
- Cabinet damage
- Scratched flooring
- Chipped tile
- Door alignment
- Missing caulk
- Damaged trim
- Loose hardware
- Window concerns
- Appliance damage
- Incomplete cleaning
The blue-tape appointment may be combined with a new-home orientation.
During the orientation, the builder may explain:
- Electrical panel
- Main water shutoff
- HVAC controls
- Appliance operation
- Irrigation
- Warranty process
- Maintenance responsibilities
- Manufacturer information
- Emergency contacts
The blue-tape walk-through is useful.
It is not a substitute for a professional inspection.
One focuses heavily on finishes, operation, and orientation.
The other evaluates the home as a system.
Your punch list needs to be written and acknowledged
In one production-builder agreement reviewed for this guide, the builder was not required to correct items unless they appeared on a written punch list signed or accepted by the builder.
That gives us a straightforward rule:
Do not rely only on:
“We’ll take care of that.”
Put it on the list.
Photograph it.
Describe the location.
Keep a copy.
Confirm who received it.
Words disappear.
Documents travel with the transaction.
Punch-list work may not delay closing
This is one of the most important expectations for a new construction buyer to understand.
Many production-builder contracts state that:
- The home is complete once the Certificate of Occupancy has been issued.
- Punch-list work can survive closing.
- The builder may complete agreed work after closing.
- The buyer must still close.
- No repair money will be held in escrow.
The Christopher Alan Homes agreement expressly stated that punch-list work would not delay closing and that funds would not be escrowed for those items.
The Maronda contract similarly allowed unfinished work to be addressed through a work order for post-closing completion rather than an escrow holdback.
This does not mean we ignore incomplete work.
It means we identify it as early as possible and understand our leverage before closing.
After closing, the conversation may shift from contract performance to warranty service.
Different process.
Different department.
Different leverage.
A builder warranty is not one giant bumper-to-bumper promise
When someone tells me:
“The house comes with a warranty.”
My next question is:
Which warranty?
A new home may have several layers of coverage:
- Builder workmanship warranty
- Structural warranty
- Manufacturer warranties
- Appliance warranties
- HVAC equipment warranty
- Roof-material warranty
- Termite-treatment warranty
- FHA-required documentation
- VA-required documentation
They do not cover the same things.
They do not last the same length of time.
They do not use the same claim procedures.
One-year workmanship warranties
A one-year builder warranty commonly covers certain defects in workmanship or materials.
That does not mean the builder must correct anything the homeowner dislikes.
The warranty may exclude or limit coverage involving:
- Normal wear
- Cosmetic variations
- Landscaping
- Irrigation
- Sod
- Shrinkage
- Homeowner maintenance
- Owner modifications
- Unauthorized repairs
- Appliances
- Manufacturer products
- Abuse
- Weather
- Acts of God
The Christopher Alan Homes contract provided a one-year limited warranty for defective or nonconforming work. The builder retained discretion to repair or replace qualifying items and excluded appliances, landscaping, irrigation, trees, bushes, and sod from that workmanship coverage.
The smaller builder contract included a negotiated one-year labor or workmanship warranty.
Those are meaningful protections.
But the written warranty controls.
Not the sales conversation.
Structural warranties
A structural warranty is different from a one-year workmanship warranty.
It generally applies to specifically defined structural components and contains its own standards, exclusions, notice requirements, and claim procedures.
One local builder agreement provided seven years of structural coverage for defined defects involving:
- Foundation and concrete slab
- Structural walls
- Roof trusses
Another local transaction included a ten-year third-party structural warranty through 2-10 Home Buyers Warranty.
Ten years sounds better than seven.
But duration is only one part of the comparison.
I also want to know:
- Who backs the warranty?
- What qualifies as a structural defect?
- Is there a deductible?
- Is arbitration required?
- What movement is excluded?
- What notice is required?
- Can unauthorized repairs affect coverage?
- Is drainage-related damage excluded?
- Is soil movement covered?
- Are consequential damages excluded?
The number on the brochure is not the entire warranty.
Manufacturer warranties
Builders frequently pass through the warranties provided by manufacturers of:
- Refrigerator
- Range
- Microwave
- Dishwasher
- Washer
- Dryer
- Water heater
- HVAC equipment
- Garage-door opener
- Fixtures
- Other consumer products
The builder may expressly disclaim direct warranty responsibility for these products.
That means the buyer may need to register the equipment after closing.
Do not put every manual in a kitchen drawer and forget about it.
Take photographs of model and serial numbers.
Register the products.
Save the confirmations.
Future-you will appreciate it.
Maintenance matters
A builder warranty does not eliminate the homeowner’s responsibility to maintain the property.
Claims may be denied when damage is connected to:
- Failure to change HVAC filters
- Failure to control interior humidity
- Improper drainage
- Unmaintained caulking
- Irrigation problems
- Landscaping against the structure
- Homeowner modifications
- Unauthorized contractor work
- Failure to report the concern promptly
A warranty is protection.
It is not permission to ignore the home.
FHA new-construction documentation
An FHA buyer should not assume that a property is financeable simply because the builder says:
“We accept FHA.”
Depending on the construction stage and lender requirements, the file may need:
- Builder certification
- Plans and specifications
- Certificate of Occupancy
- FHA appraisal
- Warranty of completion
- Termite-treatment documentation
- Required inspections or certifications
- Evidence that the property meets applicable FHA requirements
HUD’s Builder’s Certification is used for applicable proposed and newly constructed properties, and HUD also maintains separate warranty and termite-protection forms for qualifying transactions.
This is one reason lender experience matters.
A lender can be excellent with ordinary FHA resale loans and still be unfamiliar with the additional documentation required for new construction.
VA new-construction documentation
VA financing can also be used to purchase qualifying new construction.
The borrower, lender, builder, property, and transaction must still satisfy applicable VA requirements.
One of the most important protections is the VA Escape Clause.
VA states that the clause must be signed by the buyer and seller on VA purchase loans when the sales contract is signed before the Veteran receives the Notice of Value. This includes new construction contracts. If the required clause is missing, the contract must be amended before closing.
In plain English, the clause helps protect the Veteran from being forced to complete the purchase solely because the agreed price exceeds VA’s established reasonable value, subject to the actual terms of the clause.
The builder’s proprietary agreement does not erase VA requirements.
But we still need to confirm that the proper VA documents and language are included.
The appraisal is not your home inspection
An FHA or VA appraiser evaluates market value and applicable property requirements.
The appraiser is not performing your complete home inspection.
A brand-new home can:
- Receive a Certificate of Occupancy
- Appraise at the purchase price
- Meet lender requirements
And still have items that should be corrected.
Different professionals.
Different jobs.
Builder incentives can create appraisal pressure
Imagine a builder is selling a home for $420,000 and offering $25,000 toward closing costs and a rate buydown.
The buyer loves the structure because it preserves savings and lowers the payment.
The appraiser still has to support the contract price.
The builder cannot increase a price every time it offers a large incentive and automatically assume the appraisal will follow.
We review:
- Comparable new-home sales
- Same-builder closings
- Competing builders
- Lot differences
- Floor-plan differences
- Upgrades
- Concessions
- Market conditions
- Whether the complete structure appears supportable
A large incentive is useful only if the transaction still works.
What happens when the appraisal is low?
Potential outcomes may include:
- Builder reduces the price
- Builder reduces the incentive
- Buyer voluntarily contributes additional cash
- Parties split the shortage
- Relevant comparable information is submitted through the proper process
- Buyer uses available financing, appraisal, FHA, VA, or contractual protections
- Contract terminates when permitted
The specific answer depends on the purchase agreement and loan program.
A standard FAR/BAR financing contingency does not work exactly like a proprietary builder contract.
A VA buyer may also have protections that do not exist in the same form on an FHA transaction.
Never assume the deposit is automatically protected.
Read the contract before the appraisal becomes a problem.
The cheapest purchase price is not automatically the best deal
Consider three similar homes.
Builder A is selling for $400,000 but offers very little toward closing.
Builder B is selling for $420,000 with $20,000 toward costs and a permanently reduced preferred-lender rate.
Builder C is selling for $410,000 and includes a refrigerator, washer and dryer, blinds, privacy fence, city water, a better lot, and a stronger warranty.
Which home offers the best deal?
I cannot answer that from the purchase price.
I need to compare:
- Monthly payment
- Cash to close
- Interest rate
- APR
- FHA mortgage insurance
- VA funding fee
- Property taxes
- Homeowners insurance
- Flood insurance
- HOA dues
- Water and sewer
- Well and septic
- Appliances
- Upgrades
- Lot
- Warranty
- Commute
- Builder history
- Contract protections
- Resale position
Purchase price is only one piece.
How I negotiate with builders
Builder negotiation is different from negotiating with a typical homeowner.
A homeowner may focus heavily on the final price because they need a certain amount of money to move.
A builder may care more about protecting the recorded sales price.
Visible price reductions can affect:
- Future appraisals
- Remaining inventory
- Buyers already under contract
- Community pricing
- Sales goals
- Financial reporting
That means a builder may be more flexible with incentives than with the price.
Depending on the builder, home, construction stage, inventory, and sales timing, we may negotiate for:
- Closing-cost contribution
- Prepaid expenses
- Discount points
- Permanent rate buydown
- Temporary buydown
- Refrigerator
- Washer and dryer
- Blinds
- Privacy fence
- Additional cabinetry
- Upgrades
- Closing-date flexibility
- Warranty language
- Blue-tape walkthrough
- Home orientation
- Independent inspection access
- Buyer-agent compensation
- Deposit amount
- Financing protections
Sometimes the best negotiation is a lower price.
Sometimes it is preserving $15,000 of the buyer’s savings.
Sometimes it is moving part of the incentive from a temporary buydown into a permanent rate reduction.
Sometimes it is getting the builder to include items the buyer would otherwise need to purchase immediately after closing.
That is the real decision.
I compare builders against each other
Local inventory creates leverage.
If one Palm Bay builder is offering:
- $20,000 toward closing costs
- A refrigerator
- A permanently reduced rate
- City water
- A better completion date
That is valuable information when speaking with another builder.
Not as a bluff.
As a real alternative.
The strongest buyer is not the person who acts desperate for one house.
It is the buyer who understands the available options and is willing to choose the transaction that works best.
Completed inventory may provide the strongest leverage
A to-be-built home gives the buyer more opportunity to select a lot, colors, and options.
A completed inventory home gives the builder something else:
Carrying cost.
The builder may already be paying:
- Interest
- Taxes
- Insurance
- Utilities
- Maintenance
- Landscaping
- HOA expenses
That does not guarantee a discount.
But a completed home that has been sitting may create more room for:
- Price movement
- Closing-cost contribution
- Rate buydown
- Appliances
- Fence
- Blinds
- Faster closing
Timing matters.
Quarter-end and year-end goals may matter.
The number of competing homes may matter.
I want to know why the builder wants this particular home sold.
Smaller builders may offer more flexibility
A smaller builder may be more willing to negotiate direct contract language.
That might include:
- Specific warranty periods
- Structural warranty provider
- Included appliances
- Blue-tape walkthrough
- New-home orientation
- Closing-cost contribution
- Preferred-lender terms
- Inspection access
A smaller builder may also use a familiar FAR/BAR agreement instead of a lengthy proprietary contract.
That can create more balanced protections.
But smaller does not automatically mean safer.
I still want to investigate:
- Contractor license
- Permit history
- Lot ownership
- Title
- Warranty provider
- Prior construction
- Included features
- Certificate of Occupancy
- Financing eligibility
- Lien exposure
- Insurance
- Completion status
Smaller can mean flexible.
It can also mean fewer layers of support if something goes wrong.
Larger builders have systems, but their contracts usually favor them
A large production builder may provide:
- Established floor plans
- Dedicated construction teams
- Preferred financing
- Formal orientation process
- Dedicated warranty department
- Established vendors
- Larger inventory
- Stronger advertised incentives
The proprietary contract may also give the builder broad control over:
- Schedule
- Materials
- Lot placement
- Design substitutions
- Inspections
- Closing
- Punch-list work
- Warranty remedies
- Buyer default
- Dispute resolution
That does not mean you should avoid larger builders.
It means you should understand the exchange.
You may receive a well-developed system and a powerful financing package.
The builder may receive significantly more contractual control.
Affiliated lenders, title companies, and service providers
Production builders may have business relationships with:
- Mortgage lenders
- Title companies
- Insurance agencies
- Smart-home providers
- Contractors
- Brokerages
- Other settlement-service providers
The incentive may depend on using one or more of those companies.
An affiliated company is not automatically a bad company.
But the relationship should be disclosed, and the buyer should understand:
- Whether use is mandatory
- Whether the incentive depends on it
- What happens if the buyer chooses another provider
- Whether the builder receives a financial benefit
- Whether the buyer can shop competing services
- How the complete cost compares
Choice and incentive are two different questions.
Homeowners insurance can be one of the biggest advantages
Florida homeowners insurance can completely change the affordability of a property.
A new home may have:
- New roof
- Current-code construction
- Modern electrical system
- Updated plumbing
- New HVAC
- New water heater
- Wind-resistant features
- Opening protection
- Improved roof-to-wall connections
Those features may help the home receive a more favorable insurance quote than an older property.
But new does not automatically mean inexpensive.
The premium can still be affected by:
- Location
- Replacement cost
- Flood exposure
- Roof shape
- Wind protections
- Distance from the coast
- Deductibles
- Coverage limits
- Insurer availability
We request the quote before closing.
Not after the keys are in your hand.
Property taxes on new construction can surprise buyers
Do not rely on the historical tax bill for the vacant lot.
Do not rely on an assessment that reflects only partially completed construction.
Do not rely on the amount the builder currently pays.
The property may not yet be assessed as a completed home.
After completion and sale, the taxable value can change substantially.
If the lender initially estimates taxes using an incomplete assessment, the buyer may receive an escrow shortage after the property is fully assessed.
That can increase the mortgage payment later.
I would rather estimate the payment conservatively from the beginning than make the home appear cheaper using a tax number that will not last.
Homestead exemption and Save Our Homes
A qualifying Florida homeowner may be eligible to file for homestead exemption after establishing the property as their permanent residence and meeting the applicable ownership and residency requirements.
Once an eligible homestead is established, Florida’s Save Our Homes protection generally limits future annual increases in assessed value under the applicable formula.
But this protection does not prevent the initial reassessment after purchase.
The previous owner’s or builder’s tax history does not transfer to you in the way many buyers assume.
Your future payment should be estimated from your expected ownership position.
Your monthly payment is the real budget
For an FHA buyer, the complete housing payment may include:
- Principal
- Interest
- FHA mortgage insurance
- Property taxes
- Homeowners insurance
- Flood insurance
- HOA dues
For a VA buyer, it may include:
- Principal
- Interest
- Property taxes
- Homeowners insurance
- Flood insurance
- HOA dues
VA does not require monthly mortgage insurance, although a funding fee may be financed unless the borrower qualifies for an exemption.
Then we account for expenses that are not inside the mortgage payment:
- Electricity
- Water and sewer
- Well treatment
- Septic maintenance
- Lawn care
- Irrigation
- Pest control
- Internet
- Routine maintenance
- Warranty service charges, when applicable
A new home can reduce near-term repair risk.
It does not eliminate the cost of ownership.
Protect your financing during construction
The same rule from my FHA and VA guides applies here.
Treat your finances like a museum exhibit.
Look, but do not touch.
While the home is being built, do not assume you can safely:
- Finance a vehicle
- Open a furniture account
- Buy appliances on credit
- Increase credit-card balances
- Cosign for somebody
- Take out a personal loan
- Quit your job
- Change how you are paid
- Become self-employed
- Move large sums without documentation
- Spend your closing funds
A home may take months to complete.
Your lender may update your credit, income, employment, debts, and assets before closing.
Approval in March does not guarantee approval in September if your financial situation changes.
What happens during the final weeks?
As the home approaches completion, several moving pieces begin happening at once:
- Builder completion notice
- Final loan conditions
- Appraisal
- Certificate of Occupancy
- Homeowners insurance
- Closing Disclosure
- Final inspection
- New-home orientation
- Blue-tape walkthrough
- Punch list
- Warranty documents
- Cash to close
- Utility setup
- Closing scheduling
This is where my role becomes much larger than opening a model-home door several months earlier.
I help coordinate the buyer, builder representative, construction team, lender, title company, inspector, insurance provider, transaction coordinator, and other professionals involved in the purchase.
Everybody has a deadline.
Everybody has a different system.
The buyer should not have to chase all of them alone.
The final walk-through is not ceremonial
Before closing, we verify that:
- The home remains in the expected condition.
- Included appliances are present.
- Negotiated items are present.
- Agreed concerns are documented.
- Major systems appear operational.
- No significant new damage is visible.
- The home is reasonably clean.
- Keys, remotes, and access devices will be provided.
- Outstanding punch-list work is identified.
- Warranty contacts and procedures are available.
On a standard FAR/BAR transaction, the buyer has contractual rights to perform a final walk-through and confirm compliance.
On a proprietary builder contract, the orientation and punch-list process may replace much of the familiar resale walk-through structure.
Either way, we show up.
What should you receive at closing?
Depending on the home and builder, the final package may include:
- Deed
- Title information
- Survey
- Certificate of Occupancy
- Builder workmanship warranty
- Structural warranty documents
- Manufacturer warranties
- Appliance manuals
- Termite-treatment documentation
- HOA documents
- Keys
- Garage remotes
- Access codes
- Paint information
- Flooring information
- Warranty contacts
- Service-request instructions
I recommend scanning the important documents and keeping them in a digital folder.
A warranty booklet you cannot find is not very useful.
What should you do after closing?
During the first several weeks, pay attention to the home.
Test and monitor:
- Faucets
- Drains
- Toilets
- Electrical outlets
- Lights
- Appliances
- Doors
- Windows
- HVAC performance
- Irrigation
- Garage door
- Exterior drainage after rain
Document concerns with:
- Date
- Photograph
- Video
- Room or location
- Written description
- Warranty-request confirmation
Do not wait 11 months to report a leak that began during month two.
Builder warranties commonly require prompt notice and reasonable homeowner maintenance.
My recommended new-construction timeline
Before visiting the builder
- Review your budget.
- Obtain financing guidance.
- Determine your comfortable payment.
- Contact me so your representation can be registered.
- Compare FHA and VA options when applicable.
Before signing
- Compare available builders and inventory.
- Review preferred-lender financing.
- Verify the complete incentive.
- Review the lot and utility setup.
- Review the features sheet.
- Understand the deposit.
- Review important contract terms.
- Confirm inspection access.
- Confirm the warranty.
- Negotiate the complete package.
During construction
- Monitor permit and construction progress.
- Maintain loan approval.
- Avoid financial changes.
- Schedule permitted inspections.
- Document significant concerns.
- Track estimated completion without treating it as guaranteed.
- Review rate-lock timing carefully.
Near completion
- Update lender documents.
- Secure homeowners insurance.
- Confirm appraisal status.
- Schedule final inspection.
- Review inspection findings.
- Attend the blue-tape walkthrough.
- Create a written punch list.
- Review warranty documents.
- Confirm the estimated cash to close.
Before closing
- Review the Closing Disclosure.
- Verify wire instructions directly with the title company.
- Conduct the final walk-through.
- Confirm included items.
- Document unresolved work.
- Transfer utilities.
- Confirm possession.
- Close and receive the keys.
After closing
- Register manufacturer warranties.
- Submit service requests promptly.
- Maintain the property.
- Track unfinished punch-list work.
- Consider an eleven-month warranty inspection.
- File for homestead exemption when eligible.
That is the complete process.
Not just tour, sign, and hope.
Questions to ask before signing a builder contract
About the home
- Is it completed, under construction, or not started?
- What exact floor plan and elevation are included?
- Is the plan mirrored?
- Which side is the garage on?
- What features are standard?
- Which model-home features are upgrades?
- Which appliances are included?
- Are blinds included?
- Is the refrigerator included?
- Are the washer and dryer included?
- Are gutters included?
- Is irrigation included?
- Is a fence included?
About the lot
- Is there a lot premium?
- Is the home on city water, sewer, well, or septic?
- Is water-treatment equipment included?
- Where are the septic tank and drain field?
- Is flood insurance required?
- Are there drainage easements?
- Where will the home sit?
- Which trees will remain?
- Are additional clearing or driveway costs possible?
- Can the lot accommodate a pool or fence?
About the money
- What is the complete purchase price?
- What deposit is due?
- Is the deposit refundable?
- Where is it held?
- Is an additional deposit required later?
- What financing deadline applies?
- What is the builder contributing?
- Can the contribution pay prepaids?
- Can it pay discount points?
- Does it require the preferred lender?
- Does it require a particular title company?
- What happens to unused incentive money?
- Is the advertised rate permanent or temporary?
- What is the APR?
- What will the actual monthly payment be?
About construction
- What is the estimated completion?
- What is the contractual completion deadline?
- Which delays are permitted?
- Who controls the closing date?
- How much notice will the buyer receive?
- Are there penalties if the buyer or lender is not ready?
- Can the builder substitute materials?
- Can the floor plan be mirrored?
- What constitutes completion?
About inspections
- Is a pre-drywall inspection allowed?
- Is a final private inspection allowed?
- How must it be scheduled?
- What insurance must the inspector carry?
- Can the buyer attend?
- How much advance notice is required?
- Will the builder review the report?
- Is the builder required to repair everything reported?
- Can unresolved work delay closing?
- Can repair funds be held in escrow?
About the warranty
- What does the one-year warranty cover?
- What is excluded?
- Is landscaping covered?
- Is irrigation covered?
- Are appliances covered by the builder?
- How long is structural coverage?
- Who backs the structural warranty?
- How are claims submitted?
- Is there a deductible?
- Is arbitration required?
- What maintenance is required?
- Can owner-performed work affect coverage?
That is how you understand what you are buying.
My honest advice
New construction can be an excellent opportunity for an FHA or VA buyer.
You may be able to purchase a home with:
- Modern construction
- Lower immediate repair risk
- Favorable insurance features
- Builder warranty
- New appliances
- Significant seller-paid costs
- A permanently reduced interest rate
- Less cash needed at closing
But the largest incentive is not automatically the best deal.
The lowest advertised rate is not automatically the cheapest loan.
A Certificate of Occupancy is not a home inspection.
A blue-tape walkthrough is not a complete inspection.
A builder warranty is not unlimited protection.
And a friendly builder sales representative is not your buyer’s agent.
The right new construction purchase is the one where the home, payment, contract, incentive, lot, lender, insurance, timeline, and warranty all work together.
That is what I help you evaluate.
How I help Palm Bay new-construction buyers
My job begins before we enter the model home.
I help buyers:
- Understand what they can comfortably afford
- Connect with an experienced FHA or VA lender
- Compare the preferred-lender package against other financing
- Identify completed, under-construction, and upcoming inventory
- Compare builders and floor plans
- Review lot, utility, well, septic, and flood considerations
- Investigate permits and property information
- Review the important business terms of the builder’s contract
- Negotiate price, closing costs, rate buydowns, appliances, fences, upgrades, and other incentives
- Coordinate independent inspections
- Attend the blue-tape walkthrough and orientation
- Document punch-list concerns
- Track lender, appraisal, title, insurance, and construction deadlines
- Estimate property taxes and the complete payment
- Help protect the buyer’s financing and deposit position
- Stay involved through closing and possession
Sometimes I help a buyer negotiate a better price.
Sometimes I negotiate enough closing-cost assistance for them to preserve most of their savings.
Sometimes I show them that the builder advertising the lowest rate is not offering the best complete package.
Sometimes the most valuable thing I do is identify a problem before they sign.
That is the point.
Ready does not have to mean today
You do not need perfect credit.
You do not need to know which builder you want.
You do not need to understand every FHA or VA guideline before we speak.
You may be ready in 30 days.
You may need six months.
You may need to reduce credit-card balances, save a deposit, improve your credit score, resolve VA entitlement, or compare financing options.
That is okay.
We can build the plan first.
Then find the home.
Because a beautiful model home you cannot comfortably finance is still just a field trip.
Frequently Asked Questions About Buying New Construction in Palm Bay
Can I use an FHA loan to purchase a new construction home?
Yes. FHA financing can be used to purchase an eligible completed or newly constructed home when the buyer, property, builder documentation, appraisal, and lender requirements are satisfied. Depending on the construction stage, additional certifications, warranty documents, completion evidence, and termite-treatment documentation may be required.
Can I use a VA loan to purchase new construction?
Yes. Eligible Veterans and service members can use VA financing to purchase qualifying new construction. The buyer, lender, builder, property, appraisal, warranty documents, and contract must meet applicable VA requirements.
Does a VA new construction contract need an Escape Clause?
VA states that its Escape Clause is required when the purchase contract is signed before the Veteran receives the Notice of Value, including contracts for new construction.
Do I need a Realtor when buying directly from a builder?
You are not generally required to use a Realtor, but the builder’s representative works for the builder. Your own agent can help compare builders, analyze financing, review important contract terms, negotiate incentives, coordinate inspections, monitor deadlines, and protect your interests throughout the transaction.
Does using a Realtor increase the builder’s price?
Builders generally establish how cooperating-broker compensation will be handled. The practical issue is making sure your agent is properly registered under the builder’s rules before or during your first contact. Attempting to add representation after negotiating or signing may create problems.
Will the builder pay all of my closing costs?
Some builders will pay a substantial portion of eligible costs. However, “all closing costs” must be defined. The contribution may exclude property taxes, homeowners insurance, prepaid interest, escrow reserves, or other expenses. It may also depend on using the builder’s preferred lender.
Can I use builder incentives for my FHA down payment?
Builder contributions generally cannot simply replace the buyer’s required minimum investment. They may be used for eligible closing expenses, prepaids, discount points, and other permitted costs, subject to FHA and lender rules.
Should I use the builder’s preferred lender?
The preferred lender may offer valuable pricing or access to builder incentives. The complete comparison should include interest rate, APR, points, fees, mortgage insurance, payment, cash to close, rate-lock period, underwriting strength, and communication.
Should I inspect a brand-new home?
Yes. Municipal inspections do not replace an independent inspection performed for the buyer. The builder may have specific scheduling, licensing, insurance, attendance, and access requirements.
What is a blue-tape walk-through?
It is a detailed pre-closing review during which the buyer identifies visible finish concerns, damage, incomplete work, and other items for the builder’s punch list. It is often combined with a new-home orientation but does not replace a professional inspection.
Can unfinished punch-list work delay closing?
Often not. Many production-builder contracts state that the home is considered complete once a Certificate of Occupancy is issued and that punch-list work may be completed after closing without delaying the transaction or creating a repair escrow.
How long does new construction take in Palm Bay?
It depends on the construction stage, permitting, labor, materials, utilities, weather, inspections, site conditions, and lender requirements. A sales estimate may be several months, while the contractual completion period may be significantly longer.
Are all Palm Bay new homes on city water and sewer?
No. Utility combinations vary throughout Palm Bay. A home may have city water and sewer, city water with septic, or private well and septic. Availability should be verified for the specific property.
Does a new home require flood insurance?
That depends on the flood designation, lender requirements, elevation information, and insurance underwriting. A home outside a mandatory flood zone may still have flood exposure.
How long does a new-home warranty last?
It varies. A builder may provide one year of workmanship coverage and a separate seven- or ten-year structural warranty. Appliances and equipment are often covered under manufacturer warranties. The written warranty documents establish the actual coverage.
Will my property taxes be based on the vacant lot?
Not permanently. Once construction is completed and the property is sold, it may be reassessed as a completed home. Buyers should not base the long-term payment on a historical vacant-land or partially completed tax bill.
Can I negotiate with a production builder?
Yes. Depending on the home and market, the builder may be more willing to negotiate closing costs, financing, appliances, upgrades, or other incentives than to make a large visible reduction in price.
When should I contact my Realtor?
Before your first visit, online inquiry, registration, or appointment with the builder. That gives us the best chance to register your representation properly and evaluate the transaction from the beginning.
About Donell Knight II
Donell Knight II is a Brevard County Realtor with Blue Marlin Real Estate who helps FHA, VA, first-time, relocation, and new-construction buyers throughout Palm Bay and Florida’s Space Coast.
Born and raised in Brevard County and a Southeast Palm Bay resident since 2008, Donell’s approach goes beyond opening doors. He helps buyers understand financing, compare builder incentives, evaluate important contract terms, coordinate inspections, estimate ownership costs, negotiate the complete transaction, and make informed decisions from the first consultation through closing.
Thinking about purchasing a new construction home in Palm Bay or Brevard County? Contact Donell before visiting the builder so your representation can be registered and the complete builder offer can be evaluated from the beginning.